
Updated 31 July 2026
Trading 212 fees are low. It really is commission-free, with no dealing commission on trades and no platform fee. But commission-free doesn’t mean cost-free. (Other fees may apply.)
There’s one separate cost that reaches almost everyone, a 0.15% charge on anything priced in another currency, plus a couple of smaller ones worth knowing so they don’t catch you out. This guide sets out exactly what you pay, what you don’t, and where the costs actually arise.
The short version: no platform fee, no dealing commission, and a 0.15% currency conversion fee whenever your money is converted into another currency (Other fees may apply). The detail is in when that conversion happens, and how to keep the avoidable costs at zero.

Key Takeaways
- No platform or account fee: you pay nothing to hold an Invest account, ISA, or pension.
- No dealing commission: buying and selling UK shares and ETFs is free. (Other fees may apply.)
- One main cost: a 0.15% currency fee applies when you buy investments priced in another currency.
- Watch card deposits: bank transfers are free, but card and mobile-wallet deposits are free only up to a limit, then carry a small fee.
How Much Does Trading 212 Cost?
| Cost | What you pay | Notes |
| Platform/account fee | £0 | Invest account, ISA, and SIPP (pension) are all free to hold |
| Dealing commission | £0 | Buying and selling UK shares and ETFs (Other fees may apply) |
| Foreign exchange fee | 0.15% | On anything priced in a non-GBP currency (e.g. US stocks), each conversion |
| Bank transfer deposit | Free | No limit |
| Card / mobile-wallet deposit | Free, then 0.7% | First £2,000 lifetime is free; 0.7% applies to card deposits after that |
| Withdrawals | £0 | Any method |
Trading 212 is one of the lowest-cost investing platforms in the UK, and for most people who invest in pounds, the running cost is effectively zero. There is no platform fee, no account fee, and no commission when you buy or sell shares and ETFs priced in pounds. (Other fees may apply)
That combination is fairly unusual. Many platforms charge either an annual percentage of your portfolio or a flat fee per trade, and it is a large part of why Trading 212 is so popular.
The practical effect is that buying £500 of a UK-listed ETF costs you £500: nothing is shaved off on the way in.
This holds across the Invest account, the Stocks and Shares ISA and the SIPP, and our guide on how to use Trading 212 puts the whole cost picture in context.
To see why that matters, compare it with a platform charging, say, 0.45% a year: on a £20,000 portfolio that is £90 every year, whereas on Trading 212 the equivalent ongoing platform cost is nothing.
Over many years, avoiding that recurring percentage is one of the larger, if least visible, savings the platform offers, because it is money that stays invested rather than being paid away annually.
The Foreign Exchange Fee
The one cost that applies to most people is the foreign exchange fee.
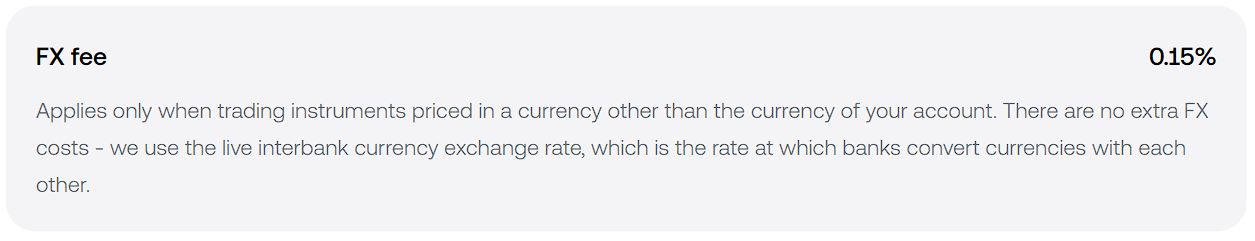
Trading 212 charges 0.15% whenever you buy or sell something priced in a currency other than pounds, such as a US stock.
In practice, that is small: invest £1,000 into a US share and the currency fee is £1.50.
The consequence only grows if you trade non-GBP holdings around often, because the 0.15% applies each time a conversion happens, so frequent buying and selling of US stocks adds up in a way a single purchase does not.
There are two ways to keep it down. If you stick to sterling-priced global ETFs, you avoid the fee almost entirely, because no conversion takes place.
And if you regularly buy foreign stocks on the Invest account, the multicurrency account lets you convert once and reuse the currency, so you pay the 0.15% a single time rather than on every trade.
Deposit Fees
Adding money by bank transfer is always free, with no limit, which makes it the method to use for regular investing and larger sums.
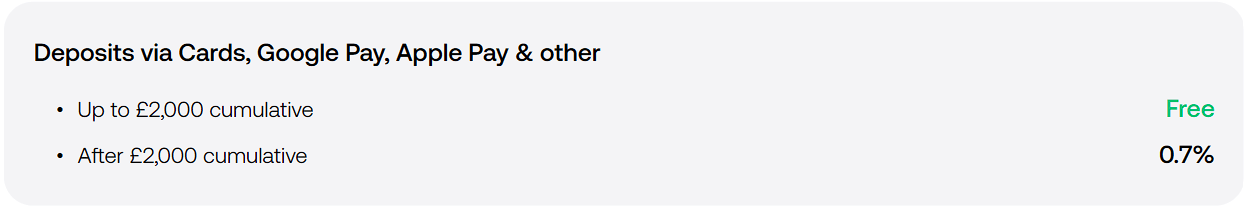
Card payments and mobile wallets like Apple Pay and Google Pay are free only up to a point: there is a combined lifetime allowance of £2,000 across those instant methods, after which a 0.7% fee applies to further card deposits.
So if you deposit £5,000 by card having never used the allowance, the first £2,000 is free and the remaining £3,000 costs about £21.
The simple way to avoid this entirely is to top up by bank transfer, which stays free no matter how much you add.
Our guide on how to deposit on Trading 212 walks through every method and when each makes sense.
Withdrawal Fees
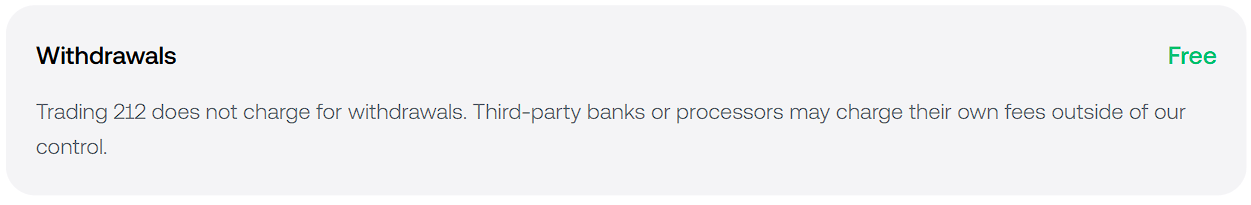
There is no fee to take your money out, by any method. The thing to be aware of is process rather than cost: Trading 212 generally returns money to the method you deposited with first, and a withdrawal can be held up while a recent sale settles, neither of which costs you anything.
You can read the full process, including the same-method rule and what the various statuses mean, in our guide on how to withdraw from Trading 212.
The takeaway for a fees guide is simply that getting your money out is free; the only thing to plan around is timing, not charges.
What About Interest and Other Costs?
Trading 212 makes some of its money in other ways, such as the small currency fee and by lending shares, but none of these adds a direct fee to a typical buy-and-hold investor using pounds.
One pass-through cost to know about is ADR fees: certain foreign companies listed on US exchanges carry a small servicing charge from a depositary bank, which Trading 212 passes on rather than charges itself.
Separately, if you hold US-listed stocks you may see dividend withholding tax, which is a tax matter rather than a platform fee, and the two are easy to confuse on the same holding.
It is also worth noting that the CFD product is a completely different service with its own costs and much higher risk; the fees in this guide are for the Invest account, ISA and pension, not CFDs.
Common Mistakes to Avoid
Two avoidable costs catch people out. The first is paying card deposit fees without realising the £2,000 allowance has run out.
A habit of topping up by card can start costing 0.7% once you pass it, whereas a bank transfer would have been free. On a £1,000 card top-up past the allowance, that is about £7 you did not need to spend.
The second is forgetting the currency fee when trading US shares frequently: at 0.15% each conversion is tiny, but repeated often it adds up, so it is worth being conscious of how often you are converting.
Both are easy to sidestep once you know they exist: use bank transfer to fund the account, and be deliberate about how often you trade non-GBP holdings.
A third, smaller point is simply checking which costs actually apply to you.
If you only ever buy UK-listed, sterling-priced ETFs and fund by bank transfer, you may pay literally nothing in fees, whereas someone trading US stocks and topping up by card pays both the currency fee and, past the allowance, the card fee.
The right habits depend on what you invest in, so it is worth knowing which of these costs your own approach triggers.
Conclusion
For a buy-and-hold investor using pounds, Trading 212 is about as cheap as it gets: no platform fee, no dealing commission, and free deposits and withdrawals by bank transfer. (Other fees may apply)
The small costs to keep in mind is the 0.15% currency fee on non-GBP investments, plus the 0.7% card deposit fee that a bank transfer avoids.
Know where those two apply, and you can keep your total cost very close to zero.
FAQ
Is Trading 212 Really Free?
For GBP shares and ETFs, there is no platform fee and no commission. The main charge is a 0.15% currency fee on non-GBP investments. (Other fees may apply)
What Is the Trading 212 Currency Fee?
It is a 0.15% fee charged when you buy or sell an investment priced in a currency other than pounds.
Does Trading 212 Charge to Deposit or Withdraw?
Bank transfers and withdrawals are free. Card and mobile-wallet deposits are free up to a limit, then carry a small fee.
Are ISA and Pension Accounts Free Too?
Yes. There is no platform or account fee on the ISA or the pension, just the same 0.15% currency fee on non-GBP investments. (Other fees may apply)